

Egypt’s external debt rose 5.3% to 164.3 billion US dollars in 2025, the World Bank said in a new report on Thursday, while the government approved spending restrictions that explicitly exempt interest and loan repayments.
The cabinet’s decision, approved on November 5, would freeze at least 20% of covered allocations for goods and services for three months, with the possibility of an extension.
The World Bank’s International Debt Report 2026, published the same day, puts the increase at 8.3 billion dollars from the end-2024 balance of 155.97 billion dollars.
However, more recent Central Bank of Egypt (CBE) figures put external debt at 166.75 billion dollars in June 2026. Against the same end-2024 baseline, the increase had reached 10.8 billion dollars, or 6.9% over 18 months, according to The Cairo Report’s calculations. The total also rose 1.5% during the first half of 2026.
The spending restrictions apply to ministries, local administration and public authorities, including economic authorities. Covered agencies, the cabinet said, would have to “defer non-urgent expenditure,” develop their own revenue sources and reduce electricity consumption by 20% and vehicle fuel use by at least 30%.
The decision also requires Finance Ministry authorization for foreign currency spending, through its financing and debt management sector, in coordination with the CBE, while increases in expenditure would require prior coordination with the ministry and submission to the cabinet.
New public investment contracts would generally be halted until June 30, 2027. However, the proposal exempts presidential and prime ministerial directives, Interior Ministry projects, and security categories.
What that would mean in practice can already be seen in the government’s accounts. In the Finance Ministry’s latest financial monthly report, the government’s interest payments on domestic and external government debt totaled 512.2 billion Egyptian pounds in July– August, after the new budget year began on July 1, against revenue of 533.2 billion pounds.
Interest equaled 96.1% of revenue and 60.3% of expenditure, exceeding the 116.8 billion pounds spent on wages more than fourfold. Although higher revenue brought the interest-to-revenue ratio down from 120.4% a year earlier, interest on debt itself rose 7%.
The same accounts record a primary surplus of 187.9 billion pounds before interest, but an overall deficit of 324.3 billion pounds after it.
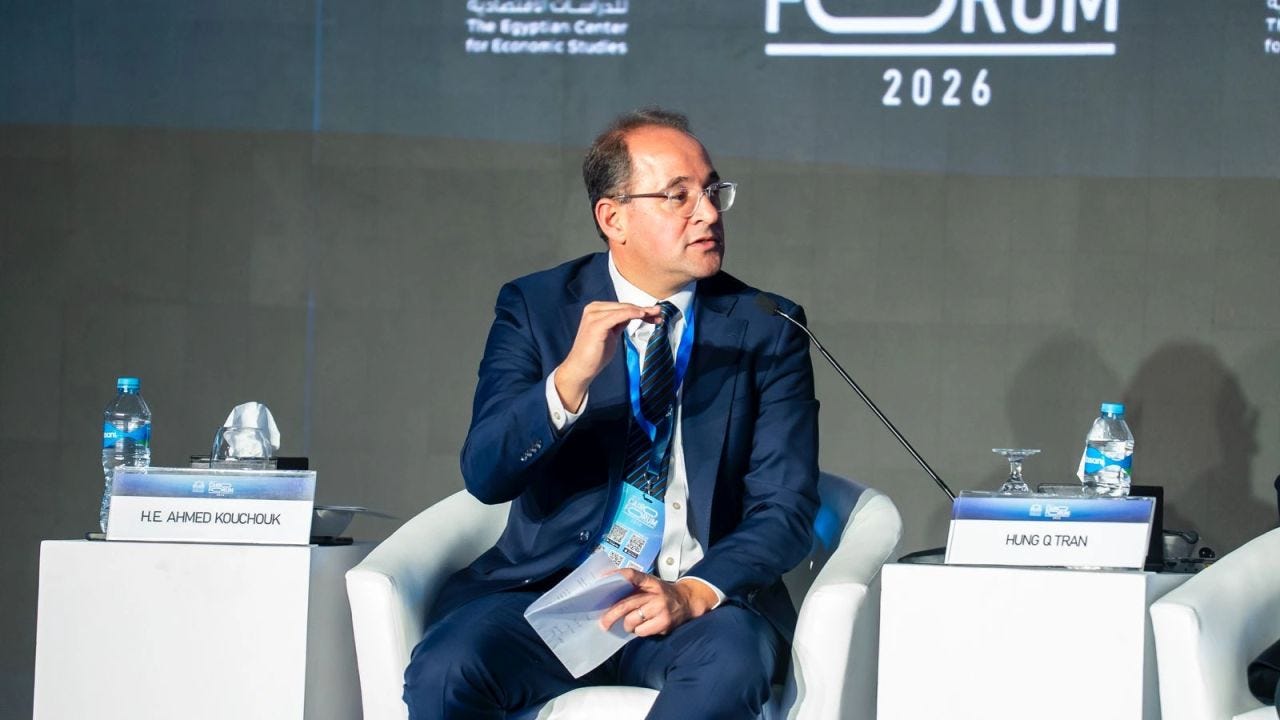
Finance Minister Ahmed Kouchouk, however, said on October 23 that external debt owed by budget sector entities had fallen by about 6.5 billion dollars over three years. “We have repaid more than we have borrowed,” he said.
Kouchouk was referring to entities within the state budget, whose external debt stood at 76.1 billion dollars in June, but excludes the central bank, banks and other borrowers included in Egypt’s total external debt, meaning that the reduction promoted covers less than half of all external debt.
The report groups 127 billion dollars, about 77% of Egypt’s external debt, under public and publicly guaranteed obligations, including International Monetary Fund (IMF) credit and special drawing rights allocations. Of that amount, private creditors held 51.2 billion dollars, multilateral institutions 41.9 billion dollars, and bilateral lenders 33.8 billion dollars.
The World Bank’s International Bank for Reconstruction and Development accounted for 12.5 billion dollars, while Russia and Saudi Arabia were the largest individually identified bilateral creditors, at 7.1 billion dollars and 6.4 billion dollars respectively.
Separately, Prime Minister Mostafa Madbouly described external debt as being “on a downward path” at a September 29 meeting with the president, before also citing the narrower budget balance. He linked falling debt to lower servicing costs and more money for health and education, which is an accounting sleight of hand, as The Cairo Report previously showed in a detailed breakdown of government spending.

Kouchouk also told the ‘Egypt Forum’ on October 22 that budget sector debt had fallen from about 96% of gross domestic product (GDP) in June 2023 to 81.9%, presenting Egypt’s decline against rising debt ratios elsewhere.
The ministry’s latest bulletin records an annual decline of 0.55%, from 82.5% in June 2025 to 81.95% in June 2026. Within that measure, domestic debt rose from 61.1% to 64.6% of GDP, while the external component fell from 21.5% to 17.4%.
The smaller overall ratio therefore accompanied greater reliance on domestic creditors, and by September, banking sector claims on government, net of government deposits, had reached 10 trillion pounds, against 5.54 trillion pounds in claims on the private sector.
The government’s data also puts short-term domestic central government debt at 12.24 trillion pounds in March 2026, equivalent to 89.5% of the domestic total, leaving much of that borrowing dependent on frequent refinancing.
The latest regional outlook by the IMF put Egypt’s gross financing needs at roughly 35% of GDP in 2025, banks’ exposure to sovereign debt at around 55% of their assets, and warned that higher borrowing costs could reduce private credit and “weaken investment and growth.”
Foreign borrowing carries its own costs. The World Bank report puts the average interest rate on new public and state-guaranteed external commitments from private creditors at 7.8% in 2025, against 5.1% from official lenders, including governments and international financial institutions.
In 2025, private creditors offered an average maturity of four years, compared with seven for official lenders, while charging an interest premium of 2.7%.
The Finance Ministry’s latest portfolio figures, published on November 2, put the average coupon on Egypt’s outstanding international bonds at 7.34% in June 2026, up from 7.26% in March, an increase of eight basis points.
In the latest 500 million-dollar bond reopening, announced on November 3, the 2030 and 2033 notes carried coupons of 8.625% and 9.45%.
The World Bank report also records an improvement in foreign repayment capacity, with external debt service falling to 30% of export earnings in 2025, from roughly 49% in 2024, using its measure of goods, services and income earned abroad. Still, this improvement accompanied a rising debt stock.
The Finance Ministry separately claimed in October that tax revenue increased without additional burdens. Its own fiscal report, however, attributes a considerable chunk of the increase in domestic value-added tax (VAT) receipts to changes in the law.
The government’s IMF program memorandum also lists tax measures expected to yield about 1.2% of GDP in 2026/27, including a wider VAT net, a gas tax and surcharges on state company profits.
The regional outlook credits Egypt’s energy subsidy cuts with “reducing fiscal vulnerabilities”, while acknowledging those cuts left consumers to absorb more of any increase in energy costs.
The CBE reported foreign exchange reserves of 57.5 billion dollars at the end of October on Thursday. Egypt nevertheless still suffers a 22.5 billion-dollar current account deficit, while banking sector net foreign assets fell 11.4% in September to 1.41 trillion pounds.
Between January and early November, the pound lost approximately 12% to 15% of its value against the US dollar, which the IMF identified, alongside higher food and energy prices, as a driver of Egypt’s inflation.
The Fund also raised its 2027 inflation projection for Egypt by 3.6% from April’s forecast, indicating a slower retreat in price pressures than previously expected.
Last month, the World Bank’s macro poverty outlook estimated that 12.5% of the population was below its 4.20 dollars a-day international poverty line in 2025/26 and projects 12.4% in 2026/27.
“Financing that merely enables countries to roll over costly debt cannot substitute for financing that expands productive capacity and raises future incomes,” the World Bank’s chief statistician, Haishan Fu, wrote in the report.