

In October 2025, the Egyptian state executed a coordinated program of fiscal extraction, property expropriation, and symbolic geopolitical performance that perfectly exemplifies the state of affairs in Sisi’s “New Republic” for the past eleven years.
This past month witnessed the simultaneous deployment of five interlocking mechanisms: international diplomatic positioning through the Sharm El-Sheikh and Egypt-European Union Summits, escalating subsidy cuts and debt accumulation, systematic land seizures through public utility designations and decrees, repeated announcements of military asset privatization with zero implementation, and selective state subsidy support. The pattern reveals the continuation of a governing apparatus exercising authoritarian capacity in extraction and expropriation while exhibiting profound institutional dysfunction in executing promised structural reforms.
Unlike narratives that naturalise authoritarian control, the state continues to show that coercive power coexists with institutional incompetence and the inability to administer policy in a coherent manner.
Geopolitical Performance & Strategic Positioning
The Sharm El-Sheikh Summit as political theater
On October 13, 2025, Egypt co-hosted the “Sharm El-Sheikh Peace Summit” alongside the United States, convening representatives from more than twenty countries to formalize the first phase of the Gaza ceasefire agreement. Egyptian President Abdel Fattah El Sisi and U.S. President Donald Trump jointly chaired the summit, which witnessed the signing of a peace declaration endorsing the agreement between Hamas and Israel, co-signed by Turkey and Qatar. The summit followed the October 9 agreement that halted hostilities after two years of conflict, implementing Trump’s “20-point peace plan.” Notably, neither Israeli nor Palestinian representatives from Gaza attended the summit directly, despite both parties being central to the agreement.
The timing of this diplomatic showcase requires contextualization within Egypt’s concurrent economic situation. The summit occurred precisely as Egypt awaited the International Monetary Fund’s combined fifth and sixth reviews of its $8 billion Extended Fund Facility program. Egypt leveraged its geopolitical utility and proximity to the ongoing Israeli destruction of Gaza, as it controls one side of the Rafah crossing, mediating Palestinian factions, coordinating with regional powers, to secure accommodations on reform implementation delays.
🔊 Dig deeper: The Summit, the Spectacle, and the Silence
Sub-imperial function & creditor accommodation
This pattern extended through the month. Nine days after the so-called peace summit, Sisi flew to Brussels for the first EU–Egypt summit. The joint statement highlighted an ambition to “deepen long-term strategic ties,” and concluded a €4 billion financial support package to bolster Egypt’s macroeconomic stability and infrastructure. While European and Egyptian officials presented the package as an investment in mutual prosperity, the funds are effectively part of a concessional loan package. By linking the support to migration control and border security, the EU implicitly treated Egypt as a garrison state, indispensable to Western strategic interests and responsible for safeguarding Europe’s border frontier.
✍️ Dig deeper: EU Hails Egypt as ‘Strategic Partner,’ Funds Repression in the Name of Stability
Fiscal Crisis Machinery & Extraction Cascades
Fuel price hike: The October episode
On October 17, the Egyptian government implemented its second major fuel price increase of the year, raising prices by EGP 2 per liter across all gasoline grades and diesel. The Automatic Pricing Committee, operating under the Ministry of Petroleum and Mineral Resources, announced price adjustments that yielded increases of 10.5% for 95-octane gasoline (EGP 19 to EGP 21/liter), 11.6% for 92-octane (EGP 17.25 to EGP 19.25), 12.7% for 80-octane (EGP 15.75 to EGP 17.75), and 12.9% for diesel (EGP 15.50 to EGP 17.50). Most dramatically, compressed natural gas (CNG) for vehicles jumped 42.9% (EGP 7 to EGP 10) per cubic meter.
The Prime Minister preemptively stated this would be “the last hike in prices if global prices hold,” a discursive framing, attributing increases to external volatility while promising future stability, which obscures the IMF structural reforms mandate. Egypt committed under its Extended Fund Facility to phasing out fuel subsidies by December 2025, with the government explicitly stating it would continue subsidizing diesel “even if this requires raising prices of other fuels above cost to help offset the subsidy.” The October increase represents the penultimate step in this phase-out trajectory, following an April 2025 increase that the government projected would yield EGP 35 billion (approximately $700 million) in budgetary savings for FY2025/26.
The distributional impacts were immediate. Within hours of the announcement, governorates across Egypt published revised transportation tariffs. The IMF’s July 2025 report had documented that a 1% fuel price increase generates 0.3-0.5% consumer price inflation through transmission mechanisms, meaning the October hike would propagate inflationary pressures of 3-6% across the consumption basket. For a population where informal sector workers, comprising the majority of employment, experienced real wage deterioration, as documented in that same IMF report, such price hikes represent a direct regressive taxation system.
Sukuk issuance & debt accumulation dynamics
To finance its budget deficit, Egypt returned to international debt markets. On 7 October 2025, the Finance Ministry priced a US$1.5 billion dual‑tranche sukuk. The issuance comprised US$700 million of 3.5‑year certificates maturing in 2029 at a 6.375 % yield and US$800 million of 7‑year certificates maturing in 2032 at 7.950%. Investor orders exceeded US$9 billion, allowing the ministry to price the tranches 20–35 basis points below comparable Eurobond yields. The weighted average cost of funding was about 7.2 %.
Baker Botts, the law firm advising on the transaction, noted that this was Egypt’s first return to the Islamic capital market since February 2023 and demonstrated strong investor appetite. The surge in orders does not necessarily indicate confidence in Egypt’s fundamentals; rather, it reflects investors’ pursuit of yield in a high‑interest environment.
The issuance was facilitated by several banks based in the Gulf Cooperation Council (GCC), highlighting the ongoing trend of Gulf capital involvement in Egypt’s debt financing. Importantly, this issuance increases total future external liabilities without providing any productive investment funds. Instead of generating future export capacity to help repay debts, it merely serves to address existing obligations and budget shortfalls.
The Finance Ministry signalled that it would issue its first domestic sovereign sukuk in November, targeting Gulf investors with yields around 20–21 %. High yields on domestic sukuk underscore the government’s desperate need for financing and the crowding‑out of private investment.
Treasury bill refinancing & the debt treadmill
Throughout October 2025, the Central Bank of Egypt conducted weekly treasury bill auctions that further revealed the mechanics of domestic debt refinancing under extreme interest rate conditions. On October 26, the CBE auctioned 91-day, 182-day, and 273-day treasury bills with average yields of 26.860%, 26.717%, and 26.190% respectively. By October 30, the CBE was offering EGP 70 billion in treasury bills across 182-day (EGP 30 billion) and 364-day (EGP 40 billion) maturities.
These figures indicate a debt refinancing treadmill. The government has to roll over short‑term bills at extremely high rates because investors demand compensation for inflation and currency risk. With domestic inflation still high, rolling over debt at such yields will massively increase future interest payments.
Regressive revenue extraction: Tolls, tariffs, & trade restrictions
Beyond fuel subsidies and debt issuance, October 2025 witnessed the proliferation of small-scale revenue extraction mechanisms that, while individually modest, collectively exemplify regressive taxation patterns. The Ministry of Transportation issued Decree No. 567/2025 imposing new road toll fees, with two collection stations charging EGP 10 for private cars, EGP 15 for light trucks, EGP 20 for buses, EGP 25 for heavy single trucks, and EGP 35 for trailers. The decree stipulates an EGP 100 fine for vehicles evading payment.
Simultaneously, the government also extended a ban on sugar exports for six months via Ministerial Decision 394/2025, citing the need to maintain domestic supply. Meanwhile, the Ministry of Agriculture Decision 446/2025 banned transporting seed cotton between Upper and Lower Egypt and mandated that cotton be processed locally.
The ban was ostensibly to regulate markets, but it effectively restricts farmers’ ability to independently negotiate better processing prices. Together, these measures reveal a state increasingly reliant on indirect taxes and commodity controls to extract revenue from ordinary citizens.
The Expropriation Cascade
October saw an acceleration of land seizures. Egypt’s Official Gazette published multiple executive decrees authorizing land expropriations under “public utility” designations, representing one of the most concentrated property seizure events documented in recent years.
Decree No. 2803/2025 declared the construction of Phase 2 of Metro Line 4 from Al-Fustat to the Omra workshop site north of the Ring Road-Cairo Suez Road intersection a “public utility” project, authorizing direct seizure by the de facto military-controlled National Authority for Tunnels of all necessary lands, structures, and properties along the route.
Decree No. 3544/2025 expanded the public utility designation for Metro Line 6 construction, adding unspecified land parcels to those previously designated under Decree 3507/2024, again authorizing direct seizure by the National Authority for Tunnels across Cairo governorate.
Decree No. 3276/2025 addressed railway infrastructure, declaring the expansion of the Mansoura-Damietta railway line a public utility project requiring land expropriations. The project is estimated to cost around 316 million euros. Funding will be sourced from a loan of 221 million euros provided by the European Investment Bank, coupled with an additional 95 million euros from the French Development Agency. Furthermore, a compensation package totaling EGP 74.92 million has been set aside for properties that have been impacted, though the method used to arrive at this amount has not been disclosed.
Decree No. 3754/2025 also classified the 23-kilometer Alexandria Ring Road project within Montazah District as public utility infrastructure, authorizing immediate seizure of lands and private properties. The decree is part of wider development plans for Alexandria, an area experiencing extensive military-led urbanization that threatens to forcibly displace approximately 6,000 families.
Decree No. 3280/2025, the government followed up with the expropriation of 89 parcels of land and private property for the new Mohamed Naguib Corridor through sections of western Alexandria.
While framed as part of the plan to modernise the city’s traffic networks, the rapid succession of these two decrees resumes a pattern of state-led value capture that underscores both the regime’s expansion in infrastructural projects and its institutional capacity to re-engineer land-based accumulation with limited transparency.
Each decree activates Law No. 10 of 1990 concerning expropriation for “public benefit,” which allows immediate seizure before compensation finalization, effectively dispossessing owners before legal recourse can take place. The military-controlled National Authority for Tunnels and other designated beneficiaries gain immediate access to properties, initiate construction, and create irreversible facts on the ground while owners navigate compensation processes that can extend years.
Privatization paralysis
In September, reports again emerged that the state planned to list five companies, including Wataniya and Safi, by the end of the month, with an aim to raise US$2.5–3 billion. This was in line with earlier statements about a wider privatization program involving numerous state-owned firms.
The announcements had initially satisfied a key IMF structural benchmark, which demands demonstrating progress on the “state ownership policy” requiring military withdrawal from sectors of the civilian economy to “level the playing field between public and private sectors.”
By the end of the month, zero transactions had occurred. Not a single company had undergone restructuring or initiated public offering procedures. The companies remained fully under National Service Projects Organization (NSPO) control, their balance sheets unprepared, their valuations unestablished, and their governance structures unreformed.
The paralysis mainly stems from military resistance to relinquishing control, coupled with institutional incapacity. The military views NSPO companies as strategic economic assets generating revenue streams, employment for demobilized officers, and influence over key sectors such as fuel distribution, food supply, and road construction. Privatization threatens these interests, explaining the long history of announced-but-never-executed sales. The government struggles to produce financial statements that would enable privatization. Many NSPO companies lack transparent accounting, commingle military and commercial activities, and enjoy regulatory exemptions that obscure true profitability.
Economic Reform as Wealth Extraction: Egypt’s Military–Investor Pipeline

In November 2016, the International Monetary Fund provided Egypt with a $12 billion loan package to implement an “ambitious economic reform program” aimed at restoring macroeconomic stability and maximizing Egypt’s economic potential. In March 2021, during his second term as president, Egyptian President Abdel-Fattah el-Sisi stood before cameras and spo…
IMF Accommodation and Program Extension
The IMF’s October 2025 posture toward Egypt’s privatization failures exemplifies geopolitical creditor accommodation. Despite the Extended Fund Facility requiring accelerated military asset sales, the Fund’s latest statements noted merely “slower progress” while signaling flexibility through combined reviews and extended timelines.
The accommodation reflects Egypt’s strategic sub-imperial value. As Gaza mediator, Suez Canal controller, and bulwark against illegal migration to Europe, Egypt provides services Western creditors prize. The IMF, responding to shareholder preferences, calibrates enforcement accordingly. Complete program suspension risks regime destabilization. The October pattern thus represents a stable equilibrium. The government implements fiscal adjustments benefiting creditors, but continues to preserve military economic dominance for the time being, despite privatization rhetoric.
Selective State Support
On 29 October 2025, the Cabinet approved a six-month extension of an EGP 50 billion tourism financing initiative. This scheme, launched in 2024, provides subsidised loans for hotel construction and renovation; the state treasury covers the interest rate differential. The subsidy extension came into effect a mere three days after the government raised fuel prices by up to 42%. The juxtaposition reveals state support bias in policymaking.
Policymakers argue that tourism revenues generate foreign currency, but there is little evidence that benefits trickle down
The EGP 50 billion subsidy warrants comparison to fuel subsidy cuts. The October 17 fuel price increase aimed to save EGP 35 billion annually in subsidy spending, extracting resources from the entire population to achieve fiscal consolidation demanded by the IMF. Three days later, the government extended subsidies to tourism capital, with the government treasury absorbing interest costs that could reach EGP 10-12.5 billion annually at commercial rates.
The government frames both as economic necessity, fuel cuts as fiscal sustainability, tourism support as growth enablement, but the distributional asymmetry is unmistakable.
Free Zones: Enclaves for capital, neglect for Labor
On the 2nd of October, Prime Ministerial decrees 62, 63, and 64 approved the establishment of three free zones.
Decision 62 granted 200,172 m² in Tenth of Ramadan City for textile production.
Decision 63 allocated 66,317 m² in the New Beni Suef industrial area for a ready‑made garments company.
Decision 64 allocated 468,510 m² in New Alamein.
Private free zones offer exemptions from customs and taxes and allow companies to hire labour under “flexible” contracts. Though presented as development schemes, free zones create enclaves disconnected from the wider economy; workers in free zones face precarious contracts, limited unionization rights, and exposure to arbitrary dismissal. The zones attract investment seeking cheap labor rather than skilled capabilities, perpetuating Egypt’s position in global value chains as a low-cost production site for investors.
Nile floods, victim blaming, and state neglect
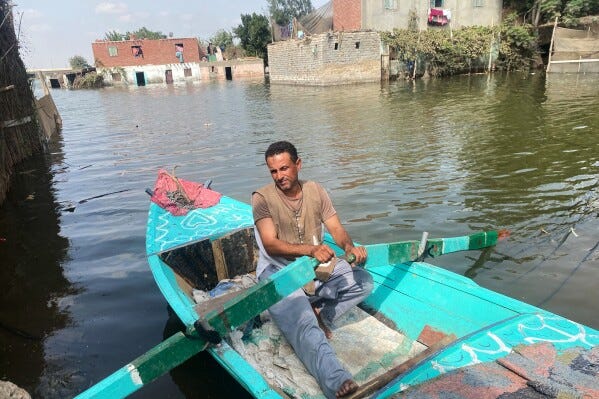
In early October, rising Nile water levels flooded 2,000 acres of riverbank lands and 131 houses in Menoufia and Beheira governorates. Residents navigated their villages by boat, lost crops and livestock, and appealed for state assistance. Instead, statements by the Prime Minister and the Minister of Water Resources blamed the victims, asserting that the flooded areas were “encroachments” and “illegally occupied by squatters,” while residents lamented that they had nowhere else to go.
Political exclusion: disqualifying parliamentary candidates
October also saw the regime’s usual political exclusion and containment. On the 24th, the Supreme Administrative Court upheld the National Elections Authority’s decision to disqualify two candidates from the Socialist Popular Alliance Party, Mohamed Abdel Halim and Haitham ElHariry, a former Member of Parliament. The court cited ElHariry’s prior exemption from military service as grounds for his exclusion, even though he had previously served a full term in Parliament without any such issues being raised. ElHariry’s defense lawyer argued this interpretation of conscription law could bar thousands of Egyptians from candidacy, violating the principle of equality and undermining the constitutional right to political participation.
Three days later, the Socialist Popular Alliance withdrew its remaining candidates in protest. These events underscore the authoritarian tendencies emblematic of the current regime; elections are managed to exclude dissenting voices while presenting a veneer of competition.
Institutional dysfunction and the governance baseline
The events of October illustrate that while the Egyptian state commands significant coercive and extractive power, it remains institutionally incompetent. For instance, the fuel pricing committee disregarded its own limit of a 10% price increase, while authorities continued to expropriate land through decrees, imposing tolls and labeling flood victims as “squatters.” The security forces maintain order, the bureaucracy manages expropriations, and the central bank oversees auctions.
However, this same state is unable to implement the announced economic reforms. The privatization of five military companies has yielded no transactions, despite Cabinet decisions and the appointment of restructuring advisors. This stagnation can be attributed to military resistance, failures in ministerial coordination, technical challenges in producing financial statements, and a political reluctance to confront entrenched interests.
Thus, October serves as a microcosm of Egypt’s political economy; it reveals the normalized functioning of an authoritarian state living under constant fiscal strain rather than a crisis or anomaly. The month’s events, such as the Gaza summit and the EU financial package on the geopolitical front, and the complete lack of progress on the domestic economic reform front, alongside selective state support favoring capital on the subsidy front, depict business as usual for a state juggling conflicting demands.
Sisi’s New Republic showcased in October its dual nature: both powerful yet weak, extractive yet incompetent, authoritarian yet accommodating. The policy developments of the past month illustrate a stable yet unsustainable balance, marking another chapter in the ongoing trajectory of a state that sustains itself through extraction, expropriation, debt accumulation, and geopolitical maneuvering, all while postponing the inevitable consequences of these strategies.
A pariah State and learning fast from Convicted Felon Fascist Republican Dictator President Donald Trump aka Agent Krasnov